After yesterday's session, the euro and the pound again gave ground to the dollar, even though both currencies tried to firm in the first half of the day. Buyers lacked ammunition — and it's not poor data to blame: even strong numbers are currently unable to outweigh expectations of tighter Fed policy, which are dictating market mood at week's end.
What did the UK data show? GDP for September rose 0.2% (vs. 0.0% expected and 0.0% previously), and GDP for Q3 increased 0.7% after 0.5% in Q2, in line with forecasts. On a year-on-year basis, economic growth accelerated to 1.9% from 1.4%. Industrial production rose 0.3% (consensus -0.3%), and manufacturing added 0.7% (expected -0.5%). The weak spot remains the trade balance: the deficit widened to £22.3bn versus an expected £19.2bn. The picture points to a reasonably solid UK recovery after a slow start to the year, and a week ago this set of figures would have supported the pound. I think it failed to do so today simply because the external backdrop outweighed domestic data.
That backdrop was created by the US side. Weekly initial jobless claims rose to 200k (vs. 195k expected), with last week's figure revised to 191k from 189k — the prior low since 1969. Continuing claims fell to 1,697k (expected 1,720k). The labor market remains tight, which helped the dollar hold its ground. In my view, Fed speakers had an even bigger impact on dollar buying than the data itself.
The dynamic matters. Mary Daly recently thought policy was well placed, yet she now says further tightening will be required because price pressures have spread beyond tariff? and energy?related sectors and firms are increasingly passing costs on to consumers. John Williams urged patience in September; in October, he allowed for one hike this year, but now calls inflation too high even on recent readings and speaks of the need for action. Beth Hammack previously favored a restrictive stance and voted to raise rates; Austan Goolsbee called the inflation report worrying and warned of overheated demand. Waller has also joined them in entertaining a 50?bp move. The tone has shifted among officials who were more cautious only recently, and that is the week's main development.
The implication is clear: the market now prices three 25?bp hikes — one in December and two more at meetings next year (priced as January and March in futures). Recall the policy rate is currently 3.75–4.00%, and the probability of a December move was already estimated at 96.3% before the CPI release. After a CPI that surprised on the upside for the third month running, a 25?bp hike in December can be considered fully priced. Notably, Fed Chair Waller has taken a defensive posture, makes few public appearances and offers no projections or rate guidance. The market therefore focuses on statements from other officials, and even non?voting FOMC members are now setting the tone.
As for today's calendar, the revised euro?area Q3 GDP report in the first half of the day will attract attention. Confirmation of 0.4% growth (as in the flash estimate) is expected after 0.6% in Q2, i.e., a slowdown is evident, with a year?on?year rate of about 1.3%. Employment is forecast to rise 0.2% q/q. For the euro, this is more background than a driver: the ECB deposit rate is 2.50%, a lift to 2.75% is expected on December 17, and preliminary October inflation is seen at 4.0% vs. 3.8% previously. A result in line with expectations changes little; a downward revision would bolster the argument that growth is lagging inflation and remove support for the euro. Any upside surprise would likely help only briefly.
The main event today is US PPI. October is forecast at 0.4% m/m and 6.6% y/y after 1.3% and 6.3% in September, with core PPI seen at 0.3% m/m after 0.7% and 5.0% y/y. September's surge — the largest since March 2022 — was almost entirely driven by fuel, with gasoline up 20.3%. That earlier spike gave only temporary dollar support and did not translate into gains versus the euro and pound. Now it's different: the market has already priced in a hawkish scenario after CPI, and if PPI again beats forecasts, the dollar will strengthen further, and EUR/GBP will continue to fall. Michelle Bowman and Susan Collins will speak later; I don't expect anything new — the tone has been consistently hawkish from Fed speakers all week.
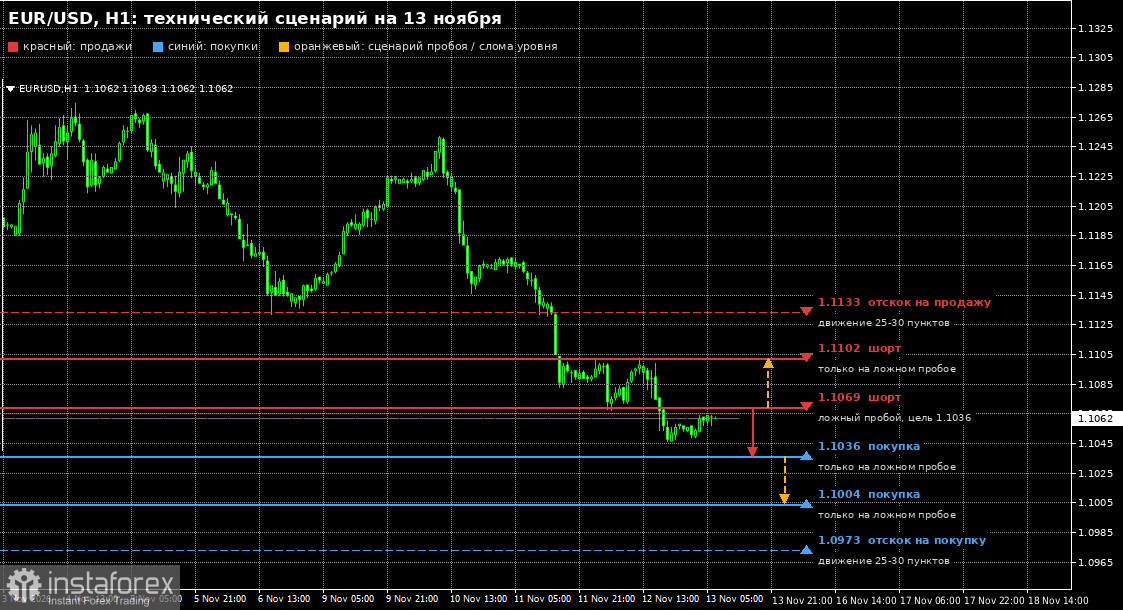
Technical picture for EUR/USD (hourly)
For long positions, consider false?break levels at 1.1036 and 1.1004 — trading here is counter?trend, with a more distant target at 1.0973 where I'd look to buy a bounce for 25–30 pips. For short positions, bears may try to defend 1.1069 on a positive European print; a false break there would indicate sellers targeting 1.1036. If no sellers appear at 1.1069, a late?week correction could reach 1.1102. Shorts only on false breaks; I'd look to sell rallies from 1.1133 for 25–30 pips.
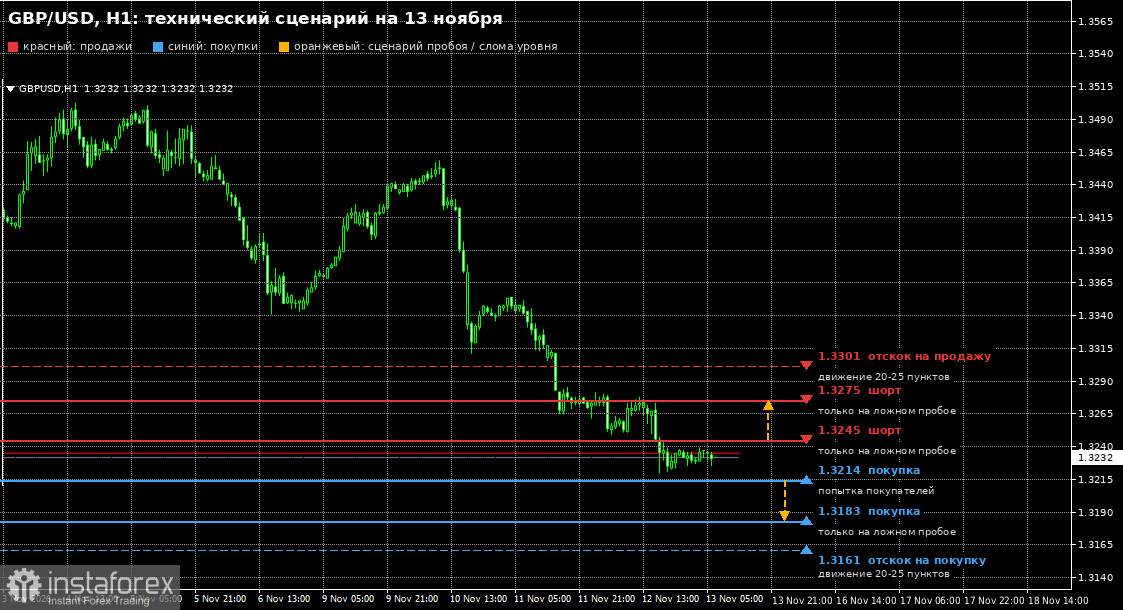
GBP/USD is following a similar pattern. After a fresh weekly low, buyers will likely try to show up at 1.3214; if not, I'd postpone buys until 1.3183 on a false break counter?trend, targeting 1.3161 for 20–25 pips. On the sell side, I'd avoid rushing near current lows — shorts should be considered only on a false break of 1.3245 or 1.3275, and I'd sell rallies from 1.3301 for 20–25 pips.
Bottom line: the dollar has the upper hand into the weekend. Three priced?in Fed hikes and the hawkish tone of officials outweigh UK data and a slowing yet still?growing eurozone. I expect a hot PPI to give markets another reason to sell EUR and GBP, with any corrective rally mainly useful for initiating shorts. A weak PPI could let buyers recoup some losses, but I don't expect a lasting reversal without a softer Fed tone.